Updated October 2026 · Fraser Bond
Insurance
Rebuild Costs and Home Insurance: Why They Matter
Why the numbers differ
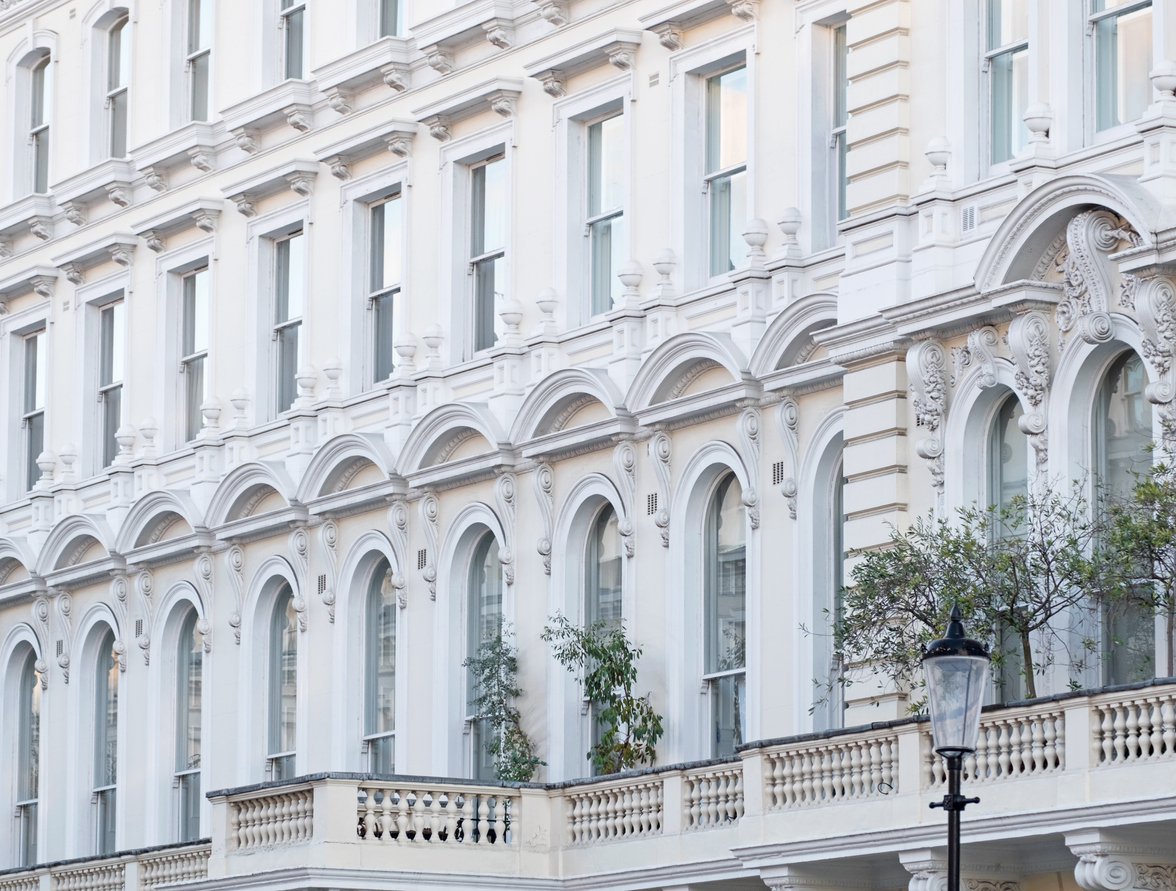
In London, land value is a large part of market value, so rebuild cost is often lower. For listed, period or unusual homes it can be higher, because of specialist materials and labour.
Under-insurance
If the sum insured is too low, insurers may apply "average" and pay only a proportion of the claim.
Property insurance through Fraser Bond
- Landlord buildings and contents cover
- Rent guarantee and legal expenses cover
- Property owners' liability
- Rebuild cost checks so you are not under-insured
- Cover placed with FCA-authorised insurers and brokers; we explain what is and is not covered before you buy
How it works
Rebuild cost is not market value. Rates vary with build type, listing status and access; a surveyor's reinstatement valuation is the reliable figure.
Frequently asked questions
Keep exploring
How to Rent an Apartment in London: What to Check FirstRENTING GUIDE
When Can a Landlord Keep Your Deposit? Your Rights in EnglandRENTING GUIDE
Weekly to Monthly Rent Conversion: The Right Way to Calculate
Browse every guide in The London Renter's Hub → · London area guides →
Handy tools
Stamp duty calculatorRental yield calculatorMove-in costsBTL deposit calculatorRefurb cost per m²
Tell us your budget and area and hear about homes first.
Where do I find my rebuild cost?
Your mortgage valuation may state one; a surveyor can give a reinstatement valuation.
Who insures a leasehold flat?
Usually the freeholder insures the building and recharges it in the service charge.
Check your cover
Send us the address and what you need. We will arrange a visit or call and give you a written quote.
Ask about coverOur property services