

HMO Conversion Opportunities UK - How to Find and Assess Development Potential
Explore HMO conversion opportunities UK investors can consider, including houses, flats and commercial properties, with practical guidance on planning, licensing, refurbishment, room layouts and HMO investment appraisal from Fraser Bond.
What Are HMO Conversion Opportunities?
HMO conversion opportunities involve adapting an existing property so it can accommodate multiple unrelated occupants who share facilities such as kitchens or bathrooms.
A typical HMO can involve:
-
A conventional house converted into a shared house
-
A large family home divided into multiple bedrooms
-
A former commercial property converted into shared accommodation
-
A building converted into bedsits
-
A property converted into specialist shared accommodation
-
A larger HMO created through redevelopment
-
An existing HMO refurbished and reconfigured
In England, a small HMO is generally a property occupied by 3 to 6 unrelated people who share facilities. HMOs with 7 or more occupants generally fall outside Class C4 and are treated as sui generis for planning purposes.
The opportunity can be attractive because an HMO may generate rental income from several occupants rather than relying on a single household.
However, converting a property into an HMO involves more than adding bedrooms. Planning, licensing, fire safety, minimum room standards, amenity space, parking and local HMO policies all need to be considered.
Why Consider HMO Conversion Opportunities UK?
HMOs can provide an alternative residential investment strategy where there is demand for shared accommodation.
Potential advantages can include:
-
Multiple rental income streams
-
Demand from students
-
Demand from young professionals
-
Demand from workers
-
Efficient use of larger properties
-
Potential refurbishment opportunities
-
Opportunities in areas close to employment
-
Potential for converting underused space
The strategy can be particularly relevant in locations with universities, hospitals, major employment centres and strong rental demand.
However, high rental income should not be assumed simply because a property can physically accommodate several people.
The local planning and licensing environment can materially affect the number of occupants and the viability of the project.
What Properties Can Be Converted Into HMOs?
Large Houses
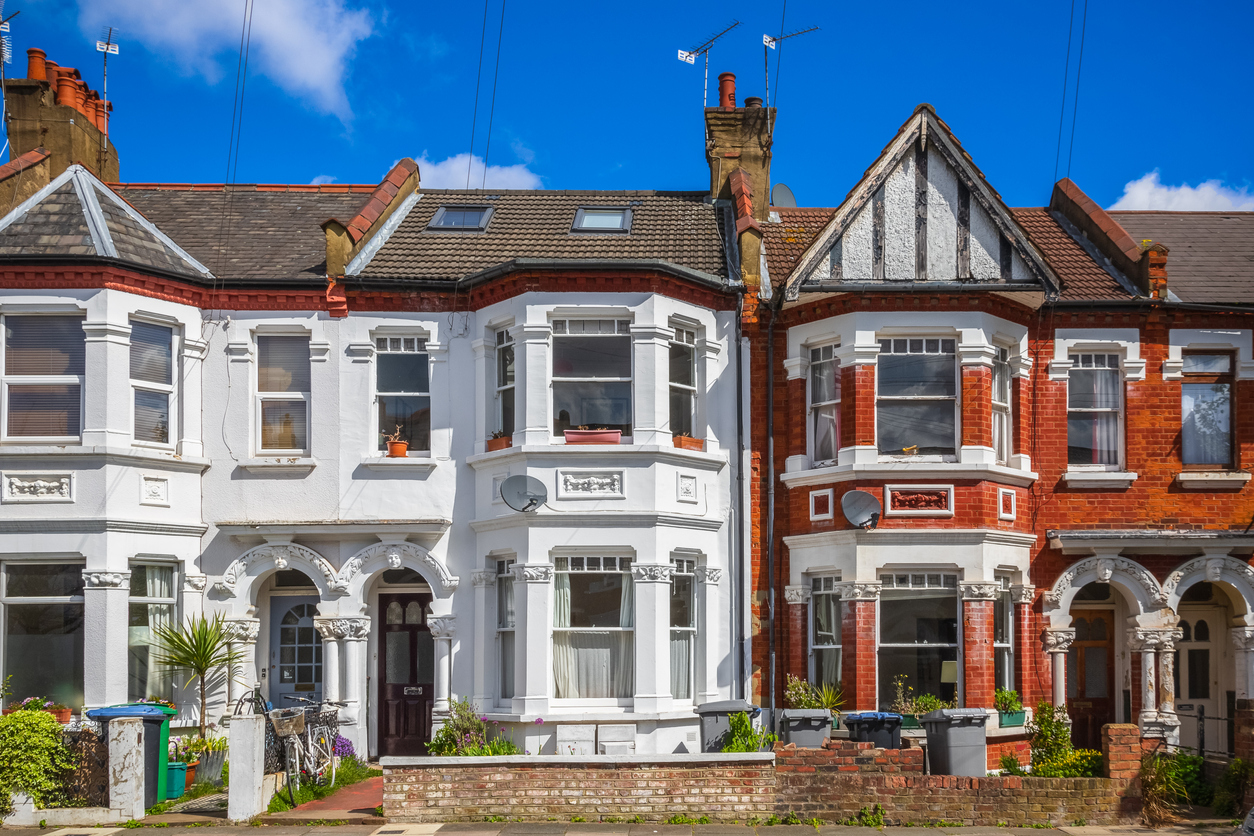
Large detached and semi-detached houses can sometimes provide good starting points for HMO conversion.
Potential characteristics include:
-
Multiple existing bedrooms
-
Large reception rooms
-
Several bathrooms
-
Large kitchens
-
Gardens
-
Off-street parking
-
Additional loft or side space
A large house may require relatively limited structural work compared with a commercial conversion, although fire safety and room standards still need to be addressed.
Houses With Extension Potential
A property with side, rear or loft extension potential may allow an investor to create additional bedrooms or improve communal areas.
Planning permission may be required for the extension depending on the circumstances.
The additional construction cost should be compared against the rental income or capital value it could create.
Former Commercial Properties
Some commercial properties can potentially be adapted for HMO or shared residential accommodation.
The planning route is more complicated than converting an existing dwelling because the proposed use may involve a change between different planning use classes.
The property's lawful existing use should be established before assigning HMO development value.
Existing HMOs
An existing HMO can itself provide a value-add opportunity.
An investor may assess whether:
-
Bedrooms can be improved
-
Communal areas can be upgraded
-
Bathrooms can be modernised
-
Energy efficiency can be improved
-
Fire safety can be upgraded
-
The property can be reconfigured
-
An extension can increase accommodation
Where an HMO already has lawful use, the planning risk can be different from creating an HMO from an ordinary dwelling.
HMO Planning Permission UK
Planning permission depends on the existing use, proposed HMO size and location.
For England, Class C4 covers small HMOs occupied by between 3 and 6 unrelated people.
National permitted development rights allow certain changes between C3 dwellinghouses and C4 small HMOs, but local authorities can remove those rights through Article 4 Directions.
This means a property may be capable of becoming a small HMO without a conventional planning application in one location but require planning permission in another.
The position must therefore be checked with the relevant local planning authority before purchase.
Article 4 Directions and HMO Conversion
Article 4 Directions are one of the most important considerations when looking for HMO conversion opportunities.
An Article 4 Direction can remove permitted development rights for a specified area.
For example, local authorities including Sheffield, Newcastle and Brighton & Hove have Article 4 controls affecting C3-to-C4 HMO conversions.
Where an Article 4 Direction applies, planning permission may be required to convert a conventional dwelling into a small HMO.
An investor should therefore check the exact property address rather than assuming that national permitted development rights apply.
HMO Conversion for More Than Six Occupants
An HMO with more than six unrelated occupants is generally outside Class C4 and treated as sui generis.
This means planning permission is normally required for the change of use.
A larger HMO can potentially generate greater rental income, but it can also involve:
-
Greater planning scrutiny
-
More extensive fire-safety requirements
-
Larger kitchens and communal areas
-
Additional bathrooms
-
Higher refurbishment costs
-
More management requirements
-
Different licensing considerations
The additional income needs to justify the increased complexity.
HMO Licensing Requirements UK
Planning permission and HMO licensing are separate matters.
GOV.UK states that a large HMO in England or Wales generally requires a licence where it is occupied by 5 or more people from more than one household who share facilities. Smaller HMOs can also require licensing depending on local authority rules.
A licence can last for a maximum of 5 years.
Licensing requirements can include standards relating to:
-
Occupancy
-
Room sizes
-
Kitchens
-
Bathrooms
-
Fire safety
-
Management
-
Gas safety
-
Electrical safety
-
Smoke alarms
Local authorities can also impose additional licensing schemes covering smaller HMOs.
An investor should therefore check the council's HMO licensing policy before purchasing.
Planning Permission vs HMO Licensing
These should never be treated as the same thing.
A property can potentially have:
-
Planning permission but no HMO licence
-
An HMO licence but unresolved planning issues
-
Lawful HMO use but require licensing
-
A lawful existing HMO use but need permission for a larger occupancy level
GOV.UK confirms that landlords should contact their local council to establish whether an HMO licence is required.
Both planning and licensing should therefore form part of the acquisition due diligence.
HMO Room Size Requirements
HMO licensing can involve minimum room-size standards.
The precise requirements depend on the applicable regulations and local licensing arrangements.
When assessing a property, measure:
-
Bedrooms
-
Communal rooms
-
Kitchens
-
Bathrooms
-
Corridors
-
Storage
-
Circulation space
Do not rely solely on an estate agent's floorplan.
A bedroom that looks commercially attractive may not be capable of being used as a legal sleeping room for the intended occupancy.
HMO Fire Safety Requirements
Fire safety is one of the most important parts of an HMO conversion.
Depending on the building and licensing requirements, works can include:
-
Fire doors
-
Fire alarms
-
Emergency lighting
-
Protected escape routes
-
Fire-resistant construction
-
Compartmentation
-
Detection systems
-
Signage
-
Emergency exits
The existing fire strategy should be assessed before refurbishment begins.
For larger or more complex HMOs, specialist fire-safety advice is particularly important.
HMO Kitchen and Bathroom Requirements
Shared accommodation needs adequate facilities for the number of occupants.
A conversion may require:
-
Larger kitchens
-
Additional bathrooms
-
Additional toilets
-
More washing facilities
-
Improved extraction
-
Increased storage
-
Larger refrigeration capacity
Adding bedrooms without upgrading shared facilities can create licensing problems and reduce the property's attractiveness to tenants.
HMO Conversion Costs UK
The cost of converting a property into an HMO varies significantly.
A development budget may need to include:
-
Purchase price
-
SDLT where applicable
-
Legal fees
-
Survey
-
Planning fees
-
Planning consultant
-
Architect
-
Building control
-
HMO licensing fees
-
Fire-safety works
-
Electrical works
-
Plumbing
-
Heating
-
Kitchen
-
Bathrooms
-
Internal refurbishment
-
Doors
-
Flooring
-
Decoration
-
Furniture
-
External works
-
Landscaping
-
Professional fees
-
Finance
-
Insurance
-
Holding costs
-
Contingency
A property requiring only refurbishment can have a very different financial profile from one requiring structural alterations and planning permission.
HMO Conversion and Property Refurbishment
Many HMO opportunities involve older properties that need modernisation.
Value can potentially be created through:
-
Reconfiguring bedrooms
-
Improving communal areas
-
Adding bathrooms
-
Modernising kitchens
-
Improving insulation
-
Upgrading heating
-
Improving fire safety
-
Replacing windows
-
Redecorating
-
Adding suitable furniture
The objective should not simply be to maximise bedroom numbers.
A well-designed HMO needs to provide comfortable accommodation that meets legal requirements and remains attractive to the target tenant market.
HMO Conversion and Extensions
An extension can sometimes increase the number of viable rooms or improve communal space.
Potential projects include:
-
Rear extensions
-
Side extensions
-
Loft conversions
-
Garage conversions
-
Garden-room development
-
Internal reconfiguration
Planning permission may be required depending on the project.
Building Regulations will also need to be considered.
An extension should only be pursued where the additional rental income or property value justifies the construction cost.
HMO Conversion and Loft Space
Large houses sometimes have unused loft areas that could potentially become additional accommodation.
However, a loft conversion may involve:
-
Structural reinforcement
-
New staircase
-
Fire protection
-
Insulation
-
Roof alterations
-
Natural light
-
Escape requirements
The feasibility should be assessed before including the loft as a rental room in the financial appraisal.
HMO Conversion Opportunities in London
London has a substantial shared-rental market, but HMO planning policies vary between boroughs.
Potential opportunities can include:
-
Large Victorian and Edwardian houses
-
Existing HMOs
-
Properties near universities
-
Properties close to employment centres
-
Former guest accommodation
-
Larger residential properties
However, Article 4 Directions and local HMO policies can significantly affect where new HMOs can be created.
A property should therefore be checked against the specific borough's planning and licensing requirements.
HMO Conversion Opportunities Manchester
Manchester has strong demand for different forms of shared accommodation in areas close to employment, universities and transport.
Potential opportunities can include:
-
Student HMOs
-
Professional house shares
-
Existing HMOs requiring refurbishment
-
Large houses suitable for conversion
-
Properties near regeneration areas
Investors should assess the relevant neighbourhood's HMO concentration and local planning policies before purchasing.
HMO Conversion Opportunities Birmingham
Birmingham contains a mixture of student, professional and workforce rental markets.
Potential opportunities can include:
-
Large residential houses
-
Existing HMOs
-
Student accommodation
-
Properties close to universities
-
Properties near employment areas
Planning and licensing requirements can differ by location, so due diligence should be property-specific.
HMO Conversion Opportunities Bristol, Leeds and Liverpool
Bristol, Leeds and Liverpool all contain areas where shared accommodation forms an important part of the private rented sector.
Potential opportunities may include:
-
Student HMOs
-
Professional house shares
-
Large Victorian houses
-
Existing HMOs
-
Refurbishment opportunities
Investors should investigate Article 4 areas, local HMO policies, licensing schemes and existing HMO concentrations.
HMO Conversion Opportunities Glasgow and Edinburgh
Scotland has a separate planning and property licensing framework.
HMO licensing requirements also differ from those in England and Wales.
Investors considering HMO opportunities in Glasgow, Edinburgh or elsewhere in Scotland should obtain advice based on the applicable Scottish planning and licensing rules.
Acquisition modelling should also account for Land and Buildings Transaction Tax rather than Stamp Duty Land Tax.
How to Find HMO Conversion Opportunities UK
Residential Property Agents
Estate agents can identify:
-
Large family houses
-
Existing HMOs
-
Properties requiring refurbishment
-
Houses with extension potential
-
Properties near universities
-
Houses with multiple bedrooms
A buyer should explain that they are looking specifically for HMO potential rather than ordinary buy-to-let property.
Specialist HMO Agents
Specialist agents can provide information about:
-
Existing HMOs
-
Licensed properties
-
HMO investments
-
Student accommodation
-
Multi-let properties
-
Development opportunities
Existing HMO income records can also help when assessing investment value.
Auctions
Large houses and former HMOs can appear at property auctions.
Potential reasons include:
-
Repossession
-
Probate
-
Estate sales
-
Refurbishment requirements
-
Investment disposals
-
Development potential
The legal pack, planning history and HMO status should be reviewed before bidding.
Planning Portals
Planning portals can reveal properties where owners have applied for:
-
C3 to C4 change of use
-
Larger HMO use
-
Extensions
-
Additional bedrooms
-
New bathrooms
-
Redevelopment
-
Retrospective HMO permission
Previous applications can reveal local planning trends and potential obstacles.
HMO Investment Appraisal
An HMO should be assessed differently from an ordinary single-let property.
Potential income can be calculated by considering:
Gross annual rent = number of rooms × monthly rent × 12
But this is only the starting point.
Deduct:
-
Management
-
Utilities
-
Council tax where applicable
-
Insurance
-
Maintenance
-
Repairs
-
Void periods
-
Licensing
-
Compliance
-
Cleaning
-
Internet
-
Furniture replacement
-
Finance
-
Service costs
The resulting net income provides a more realistic basis for comparing the invest